
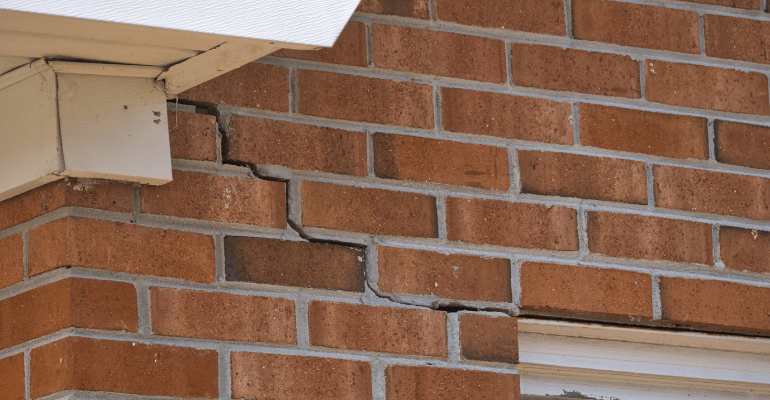
I think my house might have subsidence. Should I be worried?.
At a glance
- Insurers paid out £72 million in domestic subsidence claims during Q2 2026, with the average claim reaching a record £20,000.
- Common warning signs include diagonal cracks, sticking doors and windows, uneven floors and rippling wallpaper.
- Not every crack is a sign of subsidence. Normal settlement, ageing materials and seasonal movement can create similar symptoms.
- Subsidence can often be investigated and addressed once the underlying cause has been identified.
- A history of subsidence doesn't automatically mean a property can't be bought, sold or financed.
Finding out that your house may have subsidence can give you that sinking feeling.
Cracks in walls, sticking doors and a survey mentioning possible subsidence are enough to make any homeowner nervous. With insurers paying out record amounts for subsidence claims following recent hot, dry summers, it's unsurprising that more homeowners, buyers and surveyors are paying closer attention to the warning signs.
But while subsidence can be serious, it doesn't automatically mean expensive repairs, an unmortgageable property, or that your plans to buy, sell or remortgage are about to fall apart.
In fact, many properties showing signs of subsidence turn out to have historic movement, manageable causes or issues that can be successfully repaired.
In this guide, we'll explain how to spot the warning signs of subsidence, what causes it, what happens if it's discovered during a survey, and what it could mean for your home and mortgage.
Should you be worried about subsidence?
If you think your house might have subsidence, the short answer is to take it seriously, but don't panic.
Most cracks are not caused by subsidence. Buildings naturally move over time, particularly as materials expand and contract with changing temperatures and moisture levels.
Even when subsidence is suspected, the key questions are:
- Whether movement is historic or ongoing
- What may be causing it
- Whether further investigation is needed
- Whether there's evidence the property is stable
The answers to those questions are usually far more important than the crack itself.
What is subsidence?
Subsidence occurs when the ground beneath a property sinks, causing part of the building's foundations to move.
As foundations shift, stress can build within the structure, leading to cracks, distortion around doors and windows, uneven floors and other signs of movement.
In the UK, subsidence is often associated with clay-rich soils. Clay expands when wet and shrinks when dry, which can create movement beneath foundations during prolonged dry periods.
What are the signs of subsidence?
In many cases, the movement is gradual, which is why homeowners often notice the symptoms before they realise subsidence could be the cause.
Some of the most common warning signs include:
- Diagonal cracks in walls
- Cracks that are wider than 3mm
- Cracks that are wider at one end than the other
- Cracks appearing around doors and windows
- Cracks visible both inside and outside the property
- Doors or windows becoming difficult to open or close
- Uneven or sloping floors
- Wallpaper pulling away from walls or ceilings
The key thing to watch for is change.
A crack that's remained unchanged for years may be less concerning than one that's continuing to grow.
What should you do if you suspect subsidence?
If you've noticed potential signs of subsidence:
- Take photographs and record when changes were first noticed.
- Monitor whether cracks appear to be widening.
- Look for multiple symptoms rather than focusing on a single crack.
- Consider factors such as nearby trees, drainage issues or prolonged dry weather.
- Seek professional advice from a surveyor or structural engineer.
- Contact your buildings insurer if you believe subsidence may be involved.
The aim is to gather evidence before drawing conclusions.
What can be mistaken for subsidence?
Not every crack signals a structural problem.
Similar symptoms can be caused by:
- Normal settlement
- Thermal expansion and contraction
- Drying plaster
- Ageing building materials
- Historic movement that has already stabilised
This is why surveyors rarely diagnose subsidence based on a single crack alone.
What causes subsidence?
Several factors can contribute to subsidence.
- Clay soils - Clay-rich soils expand and contract as moisture levels change. Properties built on shrinkable clay can be more vulnerable to ground movement,
- Trees and large shrubs - During extended dry periods, trees and large plants in your garden or close to your property take more moisture out of the ground, which can cause the soil under your property to shrink further
- Leaking drains - Damaged drains can alter moisture levels around foundations or wash away supporting soil.
- Hot, dry weather - Prolonged dry spells, like recent summers, can significantly reduce moisture in clay soils, increasing the risk of movement beneath a property.
Which properties are most at risk?
Subsidence can affect almost any property, but the risk may be higher for:
- Homes built on clay-rich soils
- Older properties with shallower foundations
- Homes located close to mature trees
- Properties in areas with a history of ground movement
Research based on British Geological Survey data suggests that the UK's highest-risk areas form a band running from Dorset through London and parts of the South East, East of England and into Yorkshire. These regions contain large concentrations of clay-rich soils.
It doesn't mean every property in these areas will experience subsidence and many homeowners living in these regions never encounter any issues.
However, buyers looking at older properties, homes close to mature trees, or houses built on shrinkable clay soils may want to pay closer attention to survey findings and the warning signs outlined above.
Older properties, including some Victorian and Edwardian homes, can be more susceptible because they were built to different standards than modern homes.
What happens if a survey finds subsidence?
Surveyors are typically trying to establish:
- Whether movement is historic or ongoing
- What may have caused it
- Whether further investigation is required
Additional investigations might include drainage surveys, structural engineer reports or monitoring over time.
It's also important to remember that surveyors identify potential risks. A survey mentioning possible subsidence doesn’t necessarily mean subsidence has been confirmed or that a purchase or sale can’t proceed.
Is subsidence dangerous?
Potentially, but not always.
Some properties experience relatively minor movement that stabilises naturally or can be addressed without major works. Others may require more extensive investigation and repairs.
That's why professionals look beyond cracks alone and consider factors such as the property's age, soil conditions, drainage and nearby vegetation.
Many cases can be managed successfully once the underlying cause has been identified. The next step is understanding what repairs or remedial work, if any, may be required.
Can subsidence be fixed?
Yes. The right solution depends on what's causing the movement.
Potential remedies may include:
- Managing nearby trees
- Repairing drains
- Monitoring movement over time
- Structural repairs
- Underpinning foundations in more serious cases
Importantly, underpinning is often considered a last resort rather than the first solution.
What is heave?
Heave is effectively the opposite of subsidence and can be equally damaging.
Instead of foundations moving downwards as the ground shrinks, expanding soil pushes foundations upwards.
This can occur when clay soils regain moisture after a prolonged dry period or when mature trees are removed and local ground conditions change.
Because both heave and subsidence are caused by changes in ground movement, surveyors will often consider both possibilities when investigating structural issues.
What does subsidence mean for mortgages and property sales?
A history of subsidence can affect insurance, buyer confidence and access to finance, but it's often treated as a bigger obstacle than it actually is. For lenders, one of the most important distinctions is whether the movement is historic or ongoing.
A property that experienced movement years ago and has since been repaired and monitored successfully may present a very different risk profile to one experiencing active movement today.
Depending on the lender and individual circumstances, information that may be considered includes:
- What caused the movement
- Whether the cause has been addressed
- Whether the property is now stable
- What repairs have been completed
- What supporting evidence is available/li>
Helpful documentation may include:
- Structural engineer reports
- Building surveys
- Drainage surveys
- Repair records
- Completion certificates
- Guarantees for completed works
- Insurance claim documentation
- Monitoring reports
The stronger the supporting evidence, the easier it can be for a lender to assess the circumstances.
Many properties with historic movement, completed repairs and strong supporting evidence continue to be bought, sold and financed every year.
Subsidence doesn't always mean your options have run out
Discovering subsidence can create challenges when you're buying, refinancing or selling a property. Some lenders may be cautious, particularly where movement is ongoing or further investigations are needed.
However, a history of subsidence doesn't automatically mean a property is unmortgageable.
In our Unlocking the Unmortgageable report, we found that around 1.5 million UK homes sit outside mainstream lending criteria, often because of factors such as structural concerns, title complexities and non-standard construction.
For example, a buyer may identify a property with historic subsidence that requires repairs or further investigation before it meets the criteria of some mainstream lenders. Depending on individual circumstances, short-term bridging finance may be an option to fund a property purchase or eligible works while further investigations or remedial works are undertaken.
However, fixing the subsidence doesn’t always mean that the property will automatically meet the lending criteria of a mainstream mortgage provider. For example, a lender may have specific criteria in place around underpinned properties.
Homeowners preparing to sell also may decide to resolve the subsidence issue before putting a property on the market, as it can build buyer confidence, add potential value and may increase the number of financing options available to future purchasers.
Every situation is different, but structural issues don't always close doors. Sometimes they simply require more investigation, better documentation or a different funding route.
If you're exploring your funding options for a property affected by structural issues, we're here to help.
Similar articles
-

Built different: Funding the non-standard homes some lenders call unmortgageable
2 minPersonalIntermediariesMortgageSecure LoanBridging LoanBuy to Let -

£65,000 Refurbishment Bridging Loan helps a retired couple fix their rotten roof and sell their family home
2 minPersonalBridging Loan -

Who owns the land your property is built on? Freehold, leasehold and commonhold explained
6 minPersonalAuction FinanceMortgage
FAQs
Can I get a mortgage on a property with previous subsidence?
Can I buy a house if the survey mentions subsidence?
Can a bridging loan be used to buy a property with subsidence?
Any application would be subject to individual assessment, lending criteria and an acceptable exit strategy. There’s no guarantee that longer-term finance will be available after addressing the subsidence issues, but many lenders will consider applications.
Does a history of subsidence make a property unmortgageable?
What information will lenders usually want to see?
Any property, including your home, may be repossessed if you do not keep up repayments on your mortgage.
All lending decisions are based on lending criteria and, where applicable, subject to credit check and an assessment of individual circumstances.
All mortgages are subject to our terms and conditions.
Loans offered by Together Commercial Finance Limited are not regulated by the Financial Conduct Authority.
Articles on our website are designed to be useful for our customers, and potential customers. A variety of different topics are covered, touching on legal, taxation, financial, and practical issues. However, we offer no warranty or assurance that the content is accurate in all respects, and you should not therefore act in reliance on any of the information presented here. We would always recommend that you consult with qualified professionals with specific knowledge of your circumstances before proceeding (for example: a solicitor, surveyor or accountant, as the case may be).
